San Antonio CPA alternative

CPA in San Antonio? The CPA alternative.

Answer four quick questions. Someone outside is about to check a month.

The bridge stays. The named month has a reader.

Question 1 of 4

What did the outside reader ask for?

Question 2 of 4

Who is holding the request?

Question 3 of 4

Where did Saturday's cards go?

Question 4 of 4

What still leaves in May?

A quick check

Does their letter require a signature?

Audits, reviews, and compilations let a lender, a buyer, or a bonding company rely on the statements. Many San Antonio requests only want a month that matches the bank. The letter is what adds the signature.

The CPA alternative for that San Antonio month is a Tax CFO.

Steven Palmieri works as a Tax CFO. We close the month an outsider asked for, against the bank, before the folder goes out. The video call says whether that month can be made readable in time.

You will be talking to the Steven Palmieri practice.

Next you pick a time for a free video call with the Steven Palmieri practice. Nothing to sign, nothing to pay.

Prefer to read first? It's all below ↓

Business CPA San Antonio AlternativeBooks that match the bank

We close the books so they match the bank, set payroll up on a provider you run, and prepare the return, with Steven Palmieri, a Tax CFO and the Entrepreneur's CFO.

Close the books.

Steven Palmieri, Tax CFO

You will be talking to the Steven Palmieri practice.

A typed search on a dark card, cursor still blinking
Close the books

We are all Texans. Dallas holds the practice. The file is shared on a video call, and both ends of I-35 close on the same calendar day.

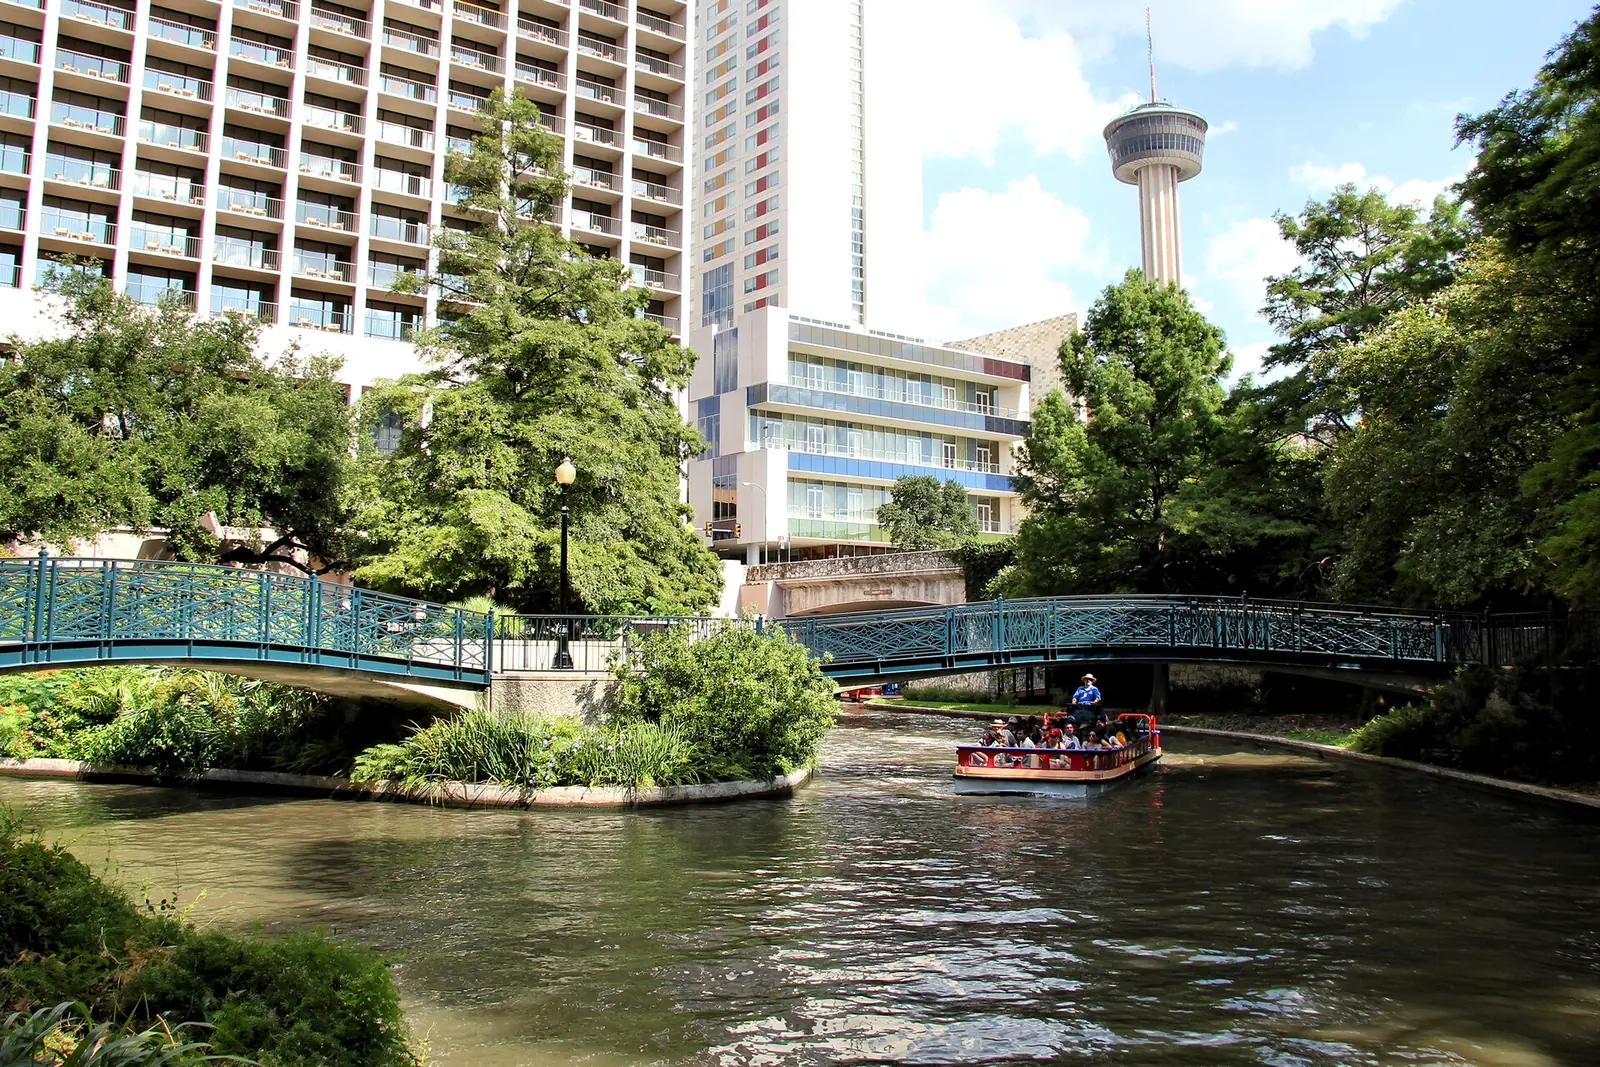
The river and a tower in San Antonio on a bright day
The river.

The river sits a level under the street, and every Texan knows that drop the first time the path goes down. We feel the same relief when a month finally sits that plain, the bank and the books saying one thing.

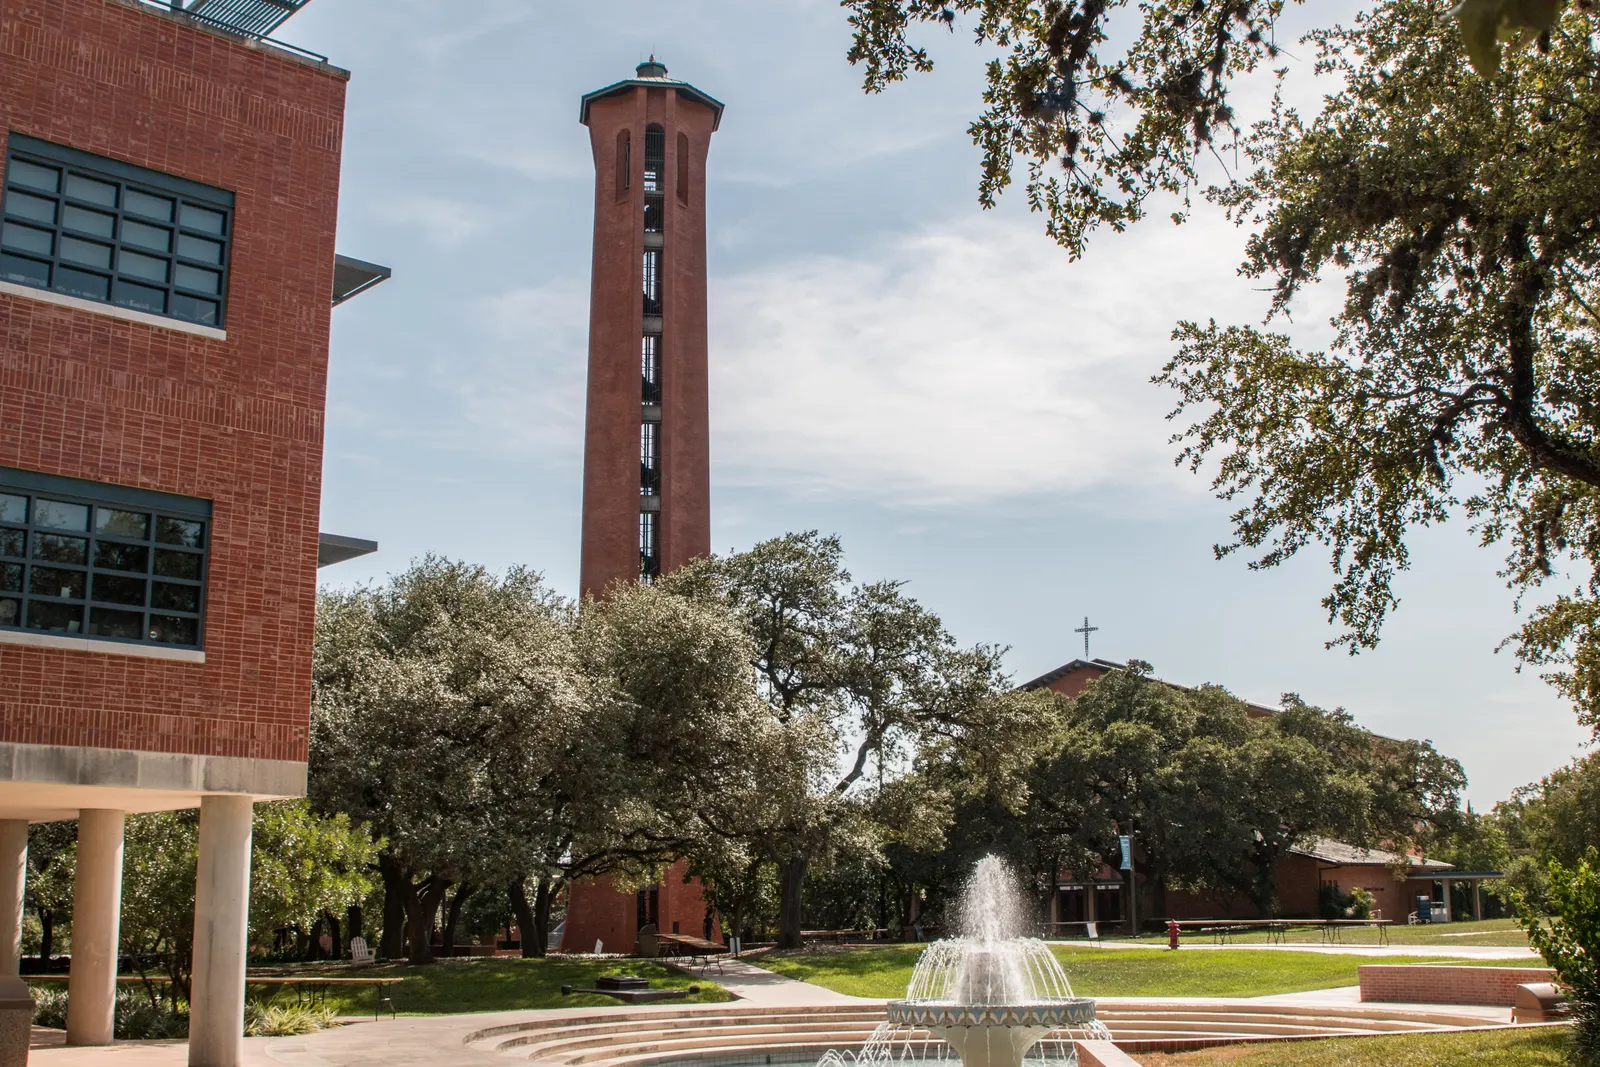
Trinity University campus in San Antonio, tower and courtyard
The campus.

Trinity sits in an old lime pit, and every Texan can feel how a rough hole became a campus people are proud to point at. A rough month can turn the same way, into a page a lender is glad to read.

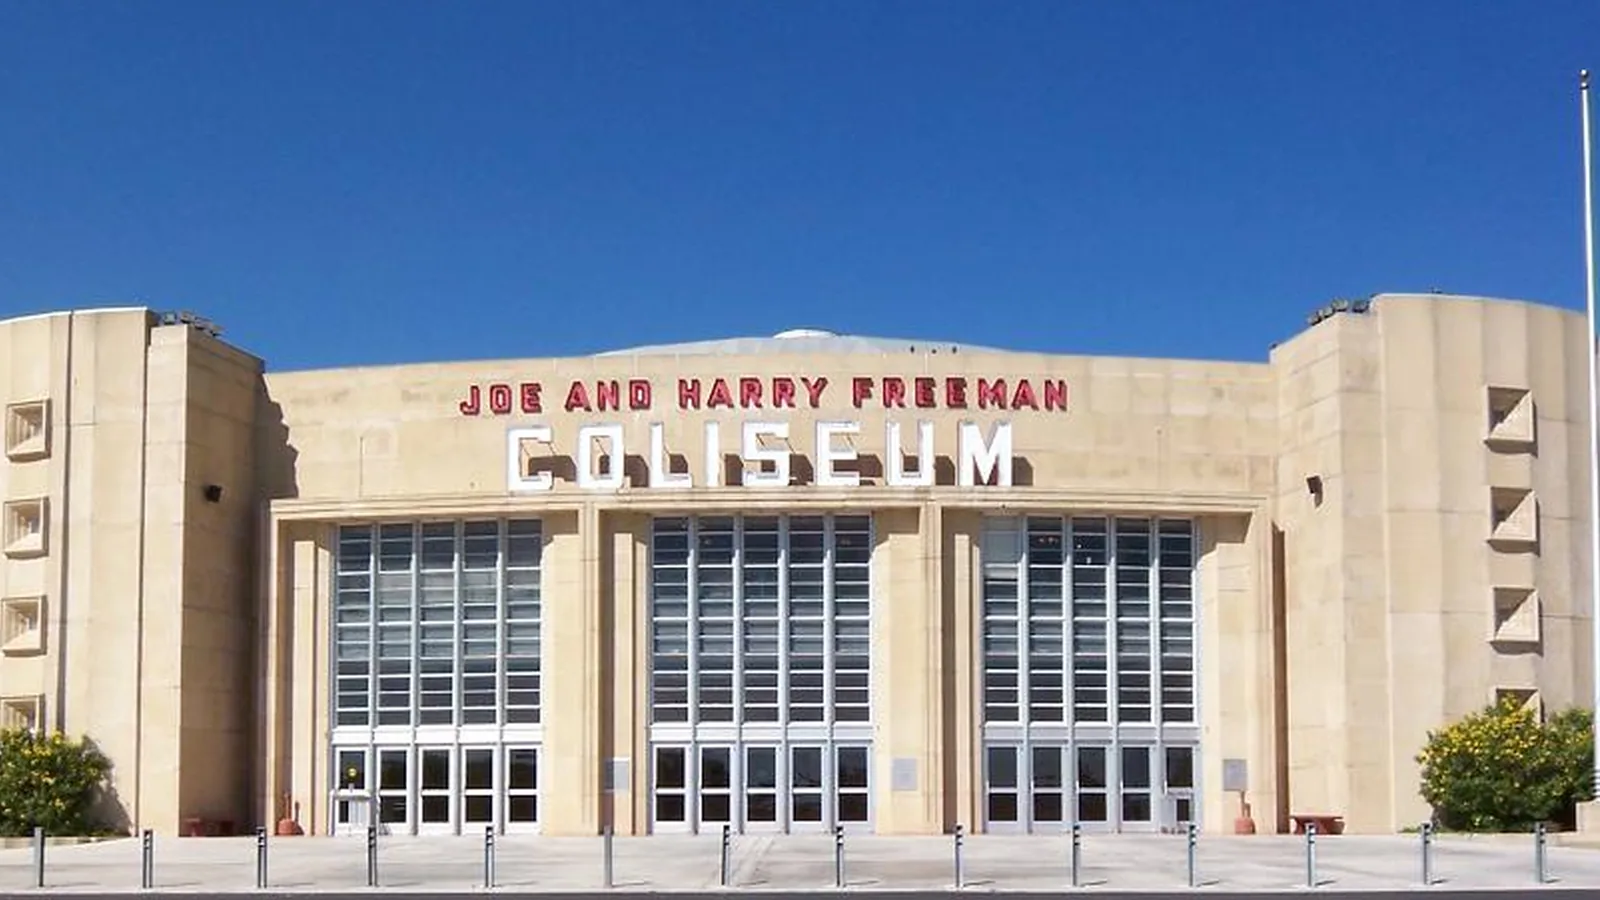
The Joe and Harry Freeman Coliseum in San Antonio, where the stock show is held
February.

February packs the Freeman Coliseum and the hotels around it, and every Texan knows that week by the noise. The card batches from those nights still want their own lines before the month is something a lender can trust.

What the request is actually asking.

Open the request that matches the paper in your hand.

  1. 1Last quarter still open

    Last quarter still open

    Last quarter still does not match the bank. A lender is asking for a quarter the books have not caught up to.

    Work begins at the last month a lender already agreed with, then steps forward one month at a time.

  2. 2Prepared by an independent

    Prepared by an independent

    The contract says prepared by an independent. Those words often want a month that ties out, and sometimes they want an opinion we do not give.

    We read the sentence with you before anyone writes a scope.

  3. 3Payday, no provider

    Payday, no provider

    Payday has a date and still has no provider. People are waiting on Friday and the provider account is not open in your name yet.

    We open that account and stop there. The weekly run stays on your login.

  4. 4An opinion on the statements

    An opinion on the statements

    The sheet asks for an opinion on the statements. Stapling an opinion onto the statements is a job this practice does not take.

    We say so on the first call. The limit is written on Disclosures.

  5. 5The transit row is missing

    The transit row is missing

    A sale inside the city is missing the transit row. The address of the sale decides which local rows belong on the return. One blended rate hides the city row from the transit row, and the filing on the 20th cannot be checked.

    We record those rows apart so the return on the 20th matches the address.

  6. 6Both returns still open

    Both returns still open

    The company return and your return are both still open. The draw you take has to land as one figure on both of those returns.

    We prepare both from the same closed months, company first.

Read the request.

Steven Palmieri, Tax CFO

Steven Palmieri, Tax CFO.

The Entrepreneur's CFO.

The name.

Payday is opened on a provider you run afterward, the month is brought to a bank match, and the return is written only after that match.

What a lender asks.

A lender rarely wants a speech about the year. The request is a quarter the bank already believes, plus the months after it if the loan will fund before the next close. We start on the page the bank has accepted and we say out loud when the later months are still open. The bank match is the part a stranger can check without a tour.

If the request also asks for an opinion stapled to the statements, that sentence is a different job. We name it on the first call and we point at the limit written on Disclosures. A bank-matched month can still be prepared on this practice. The opinion cannot.

How payday gets opened.

People notice payroll on a Friday, when a deposit is late. The work we do is earlier than that. We open the provider account in your name, we match the people to the pay items, and we stop. The weekly run stays on your login, or on the provider under your direction.

Owner draws and wages that share one year get tangled if they are sorted only in April. We split them in the month the money moved, so the company return and your return describe the same check.

Both returns.

Owner pay is the place two returns drift apart. One return calls a transfer a wage. The other calls it a draw. The IRS reads them side by side. We prepare the company return from the closed months, then the personal return from those same months, so the wage, the draw, and the distribution are not three versions of one check.

Owner pay in the months the bank has already accepted is how we sketch the next quarterly estimate, on the close call, next to the wage and the draw. That sketch happens before April, while the wage and the draw are still easy to point at. The sketch is a figure for the estimate, not a forecast of what the return will owe.

Unsigned work.

Those three statement signatures are not part of this practice. If a contract uses one of those words, the honest answer is that the signature goes to a firm allowed to give it. The rest of the request, a month that ties and a return prepared from it, can still sit with us.

The fuller limit is on the Disclosures page, in the section that says where a signature has to go. We do not spend the first screen explaining the last word of the brand. People arrive wanting a closed month, a provider account in their name, and a return built afterward.

What the fee follows.

These pages never quote a dollar amount for the work. What we can see in one month is what sets the fee. Five things move it. How many transactions land, how many balances stay open, whether payday is already on a provider, how far behind the bank the books are, and whether a job or a contract has to be shown on its own schedule.

Catching up older months is a separate conversation, priced after one real month has been in our hands. A month the bank has not accepted cannot be the source of a number a lender will trust. That older month gets closed, or you hear that a lender should not rely on the figure yet.

The May filing.

Texas entities file a franchise report in May, beside the public information report. A Texas entity under 2.65 million dollars of revenue owes no franchise tax in 2026. A goods business pays the lower margin rate, three eighths of one percent. A business that sells a service is on the higher margin rate, 0.75 percent. May 15 is the usual day, and a weekend moves the filing to the following business day.

A zero balance can still leave the franchise report due. The franchise report travels on its own and does not ride with the federal return. The page on the May report walks the sales tax rows and the property rendition that often share the spring. On the close call we also ask whether the May franchise report is yours to file.

A sale inside the city.

State sales tax is 6.25 percent. Local additions can reach 2 percent, and the combined ceiling is 8.25 percent. Inside this city those pieces include the city, VIA, and the Advanced Transportation District. County tax sits outside this sales stack. A contract that shows one flat rate has skipped the address.

We record the city piece and the transit piece apart so the return due on the 20th matches the place the sale happened. A mixed beverage tax at 8.25 percent is a different tax. It is not the local sales stack with a new name, and the books should not bury it in the same row.

The first month.

Catch-up starts only after the newest month a lender has already accepted. Everything after that is catch-up, and catch-up is its own conversation.

Payday setup creates the provider account under your name, and then stops. After that opening, payday stays on your login. The return is prepared from those closed months, so owner pay is told the same way on both returns.

A year never filed.

Sometimes the worry is not last month. It is a year that never went out. We say that plainly before we talk about a clean close on the current books. The current month still has to tie, because a late return built on a month the bank rejects is just a second problem with a date on it.

Any relief from a penalty is asked only after the return exists, and this page promises none of it. We will not invent a result. We will tell you whether the year is open, whether the months under it can be closed, and what we would need in hand before anyone talks to the agency.

Start from books you trust.

Which closed books should we open from?

Steven Palmieri, Tax CFO

You will be talking to the Steven Palmieri practice.